

 ion
An Indian property sale can become considerably more complicated when the seller is an Australian tax resident. From tax deducted at source (TDS) in India to capital gains tax in Australia, the transaction involves two tax systems, different financial years and currency considerations. DOT.in asked Aarjav Jain, executive director and NRI Tax Expert at Dinesh Aarjav and Associates Chartered Accountants, to explain what Australian-based Indians need to know before selling property in India.
What is the first tax issue an Australian-based Indian encounters when selling property in India? And how does Australian tax residency affect the transaction?
The first thing to establish is your residency. Let us say you are an Australian tax resident, and are a non-resident for Indian tax purposes. This matters because the buyer must deduct tax at source when you sell the property.
For sales before October 2026, the buyer must quote their TAN when depositing TDS; from October 2026, TAN will no longer be required.
For an Indian resident selling property, TDS is 1% of the property value. For non-residents, it is 12.5% plus surcharge and cess. The surcharge is nil below ₹50 lakh, 10% between ₹50 lakh and ₹1 crore, and 15% above ₹1 crore. With the 4% cess, the effective rates are about 13%, 14.3% and 14.95% respectively.
Australian residency also matters because Australia generally resets the property’s cost base to its fair market value when you become an Australian resident, rather than using the original Indian purchase price. Australia therefore taxes the gain arising after migration.
How is the capital gain calculated and taxed in India, including cases where the property is inherited or jointly owned?
Capital gain is broadly the sale price minus the purchase cost. For non-residents, the tax rate is 12.5% plus surcharge and cess, without indexation. For property inherited after April 2001, the cost is generally based on its value at inheritance. If inherited before April 2001, a registered valuer determines its fair market value as of April 1, 2001, which becomes the cost base.
For jointly-owned property, each co-owner is taxed on their respective share. If both owners are non-residents, each is taxed at 12.5% plus applicable surcharge and cess on their share. If one owner is a resident, that person’s share is subject to the resident rules, including 1% TDS and available indexation, while the non-resident owner’s share is subject to the higher non-resident rate.
Can the amount withheld differ from the seller’s eventual tax liability?
When a non-resident sells property, the buyer must deduct TDS at the stipulated rate. Crucially, this is calculated on the entire sale value, not merely the capital gain itself. The amount withheld can therefore be much higher than the seller’s eventual tax liability. For example, if a property bought for ₹80 lakh is sold for ₹2.2 crore, the capital gain is ₹1.4 crore. But TDS is calculated on the full ₹2.2 crore.
When the seller files an Indian tax return, any excess TDS can be claimed as a refund. The seller can also approach the jurisdictional Assessing Officer for a certificate under Section 197, commonly referred to as Form 13, before the transaction. This can allow a lower or nil TDS where justified by the actual tax liability and proposed exemptions.
Once the seller is an Australian tax resident, how is the Indian property sale treated in Australia, particularly if the property was bought before the person moved to Australia?
Australia generally resets the cost base to the property’s fair market value when the individual becomes an Australian resident. For example, if a property was bought in 2005 but the owner moved to Australia in 2015, the 2015 market value becomes the Australian cost base. If the property is held for more than 12 months, a 50% capital gains discount may apply.
The resulting taxable gain is taxed at the individual’s marginal rate plus Medicare levy. The calculation is made in Australian dollars, using exchange rates at the relevant dates. Currency movements can therefore increase or reduce the Australian taxable gain, even when the original purchase and sale were both in rupees.
If tax has already been paid in India, how does the India-Australia tax treaty and Foreign Income Tax Offset work, and can the seller still have an Australian tax liability?
India and Australia have a Double Taxation Avoidance Agreement. Tax paid in India can generally be claimed in Australia as a Foreign Income Tax Offset (FITO), subject to the applicable rules and limits. The Indian tax paid is credited against the Australian tax liability on the same income. If the Indian tax is sufficient to cover the Australian liability, there may be no additional Australian tax to pay, although the income still has to be reported. Timing can be important because India’s tax year runs from April to March, while Australia's runs from July to June. A taxpayer may therefore have to file an Australian return before the Indian tax position is finalised and subsequently amend the Australian return to claim the credit.
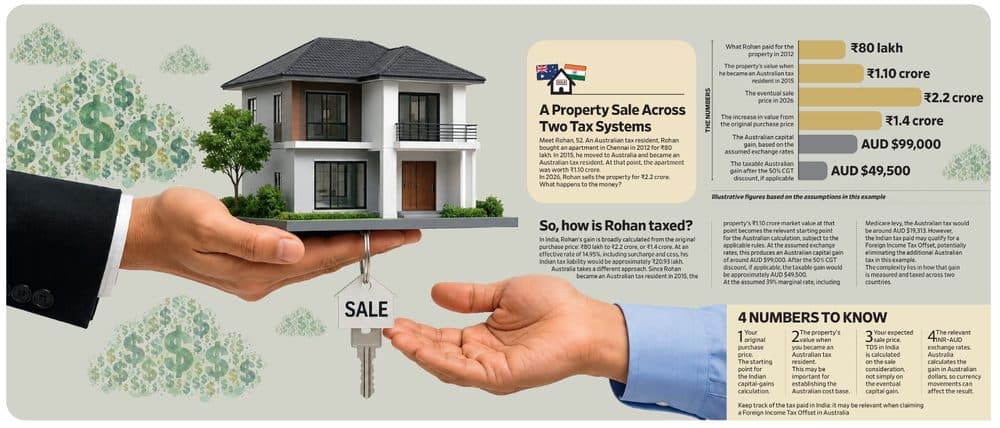
A PROPERTY SALE ACROSS TWO TAX SYSTEMS
Meet Rohan, 52. An Australian tax resident, Rohan bought an apartment in Chennai in 2012 for ₹80 lakh. In 2015, he moved to Australia and became an Australian tax resident. At that point, the apartment was worth ₹1.10 crore.
The Numbers
₹80 lakh
What Rohan paid for the property in 2012
₹1.10 crore
The property’s value when he became an Australian tax resident in 2015
₹2.2 crore
The eventual sale price in 2026
₹1.4 crore
The increase in value from the original purchase price
AUD$ 99,000
The Australian capital gain, based on the assumed exchange rates
AUD$ 49,500
The taxable Australian gain after the 50% CGT discount, if applicable
Illustrative figures based on the assumptions in this example.
So, how is Rohan taxed?
In India, Rohan's gain is broadly calculated from the original purchase price: ₹80 lakh to ₹2.2 crore, or ₹1.4 crore. At an effective rate of 14.95%, including surcharge and cess, his Indian tax liability would be approximately ₹20.93 lakh.
Australia takes a different approach. Since Rohan became an Australian tax resident in 2015, the property’s ₹1.10 crore market value at that point becomes the relevant starting point for the Australian calculation, subject to the applicable rules. At the assumed exchange rates, this produces an Australian capital gain of around AUD$ 99,000. After the 50% CGT discount, if applicable, the taxable gain would be approximately AUD$ 49,500.
At the assumed 39% marginal rate, including Medicare levy, the Australian tax would be around AUD$ 19,313. However, the Indian tax paid may qualify for a Foreign Income Tax Offset, potentially eliminating the additional Australian tax in this example.
The complexity lies in how that gain is measured and taxed across two countries.